Concierge medicine is an emerging and trending model in the American health care system, which has grown as an alternative to insurance-based health care. Nowadays, some people are choosing these membership-based models over traditional insurance-based health care.
While some concierge medicine practices may operate on a cash-only basis, many do accept and bill health insurance for covered medical services, functioning similarly to traditional practices in this regard. The good news is Concierge Medicine and Health Savings Account (HSA) can work well together for eligible expenses.
If you have a Health Savings Account (HSA) plan, knowing how it works with Concierge Medicine can help you plan your healthcare costs.
Providers mostly accept cash or credit cards, and HSA serves as a smart and viable alternative to get coverage for qualified medical expenses.
Concierge medicine takes us back in time when healthcare felt more personal and easier to reach – like how it was in the '60s when doctors came to your house to treat you. This is just one of the many benefits of having a Concierge Medicine membership.
Instead of a fee-for-service agreement employed under the insurance-based model, your provider charges you a membership fee, which can vary widely.
This fee is in exchange for a series of services under the concierge agreement. Some of the most common services include extended and same-day appointments, 24/7 access to the personal line of your provider, and more.
And the result of all the perks granted under concierge medicine? Easier access to healthcare, more time with your doctor, and a closer doctor-patient relationship.
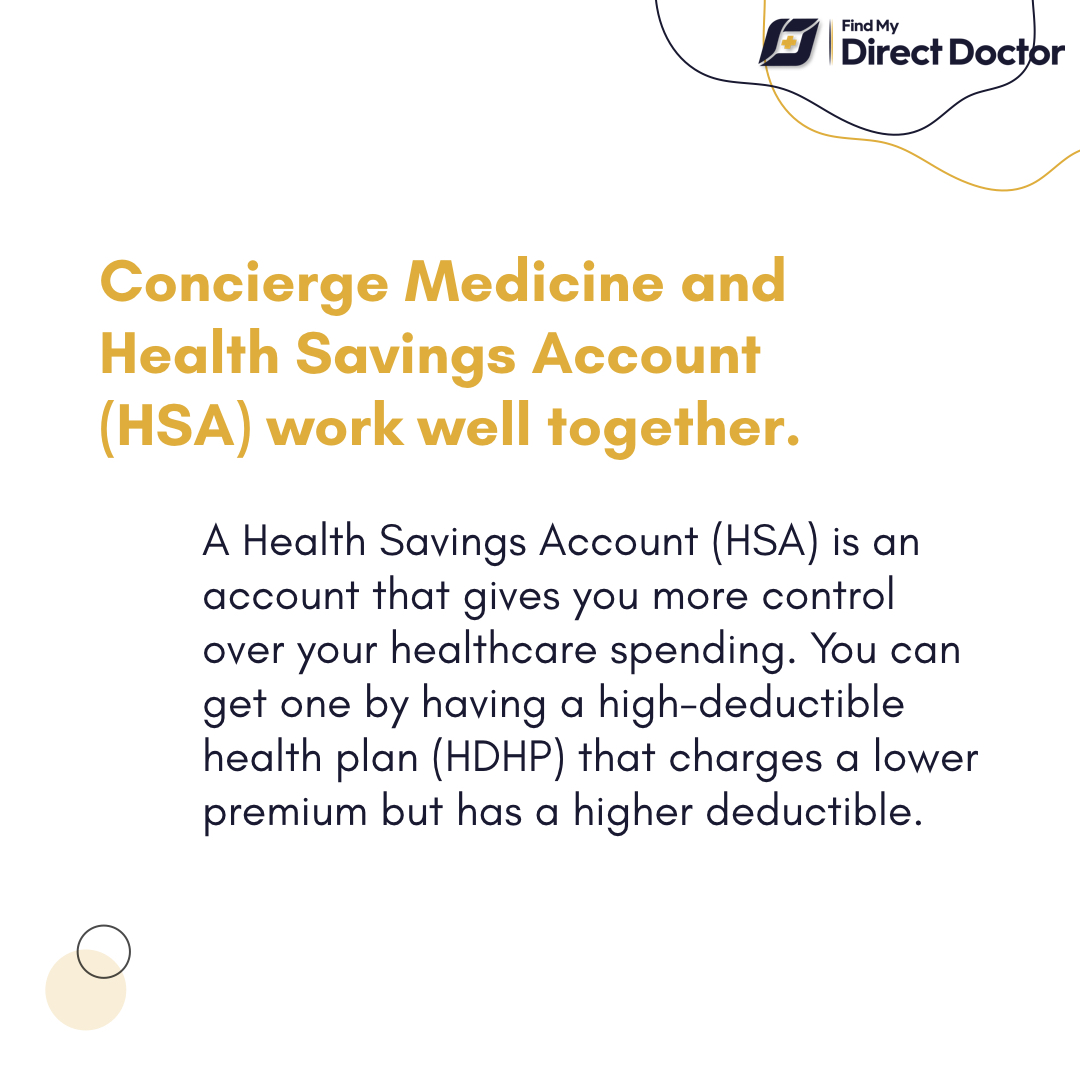
A Health Savings Account (HSA) is an account that gives you more control over your healthcare spending. You can get one by having a high-deductible health plan (HDHP) that charges a lower premium but has a higher deductible.
A higher deductible initially sounds unattractive because it means that you will have to pay more out of pocket, but that is the whole purpose of your HSA. It lets you put aside money specifically for medical expenses that you can use should you need it. As a tax-advantaged account, the government does not tax anything you put into it, including any interest you earn.
But what makes it great is your contribution here (for 2026, the maximum contribution is $4,400 for self-only HDHP coverage and $8,750 for family HDHP coverage, with an additional $1,000 catch-up contribution allowed for those age 55 and older ) comes from your untaxed income. So if you are in the 24% tax bracket, you are essentially saving a significant amount on your taxes just by setting aside money in your HSA.
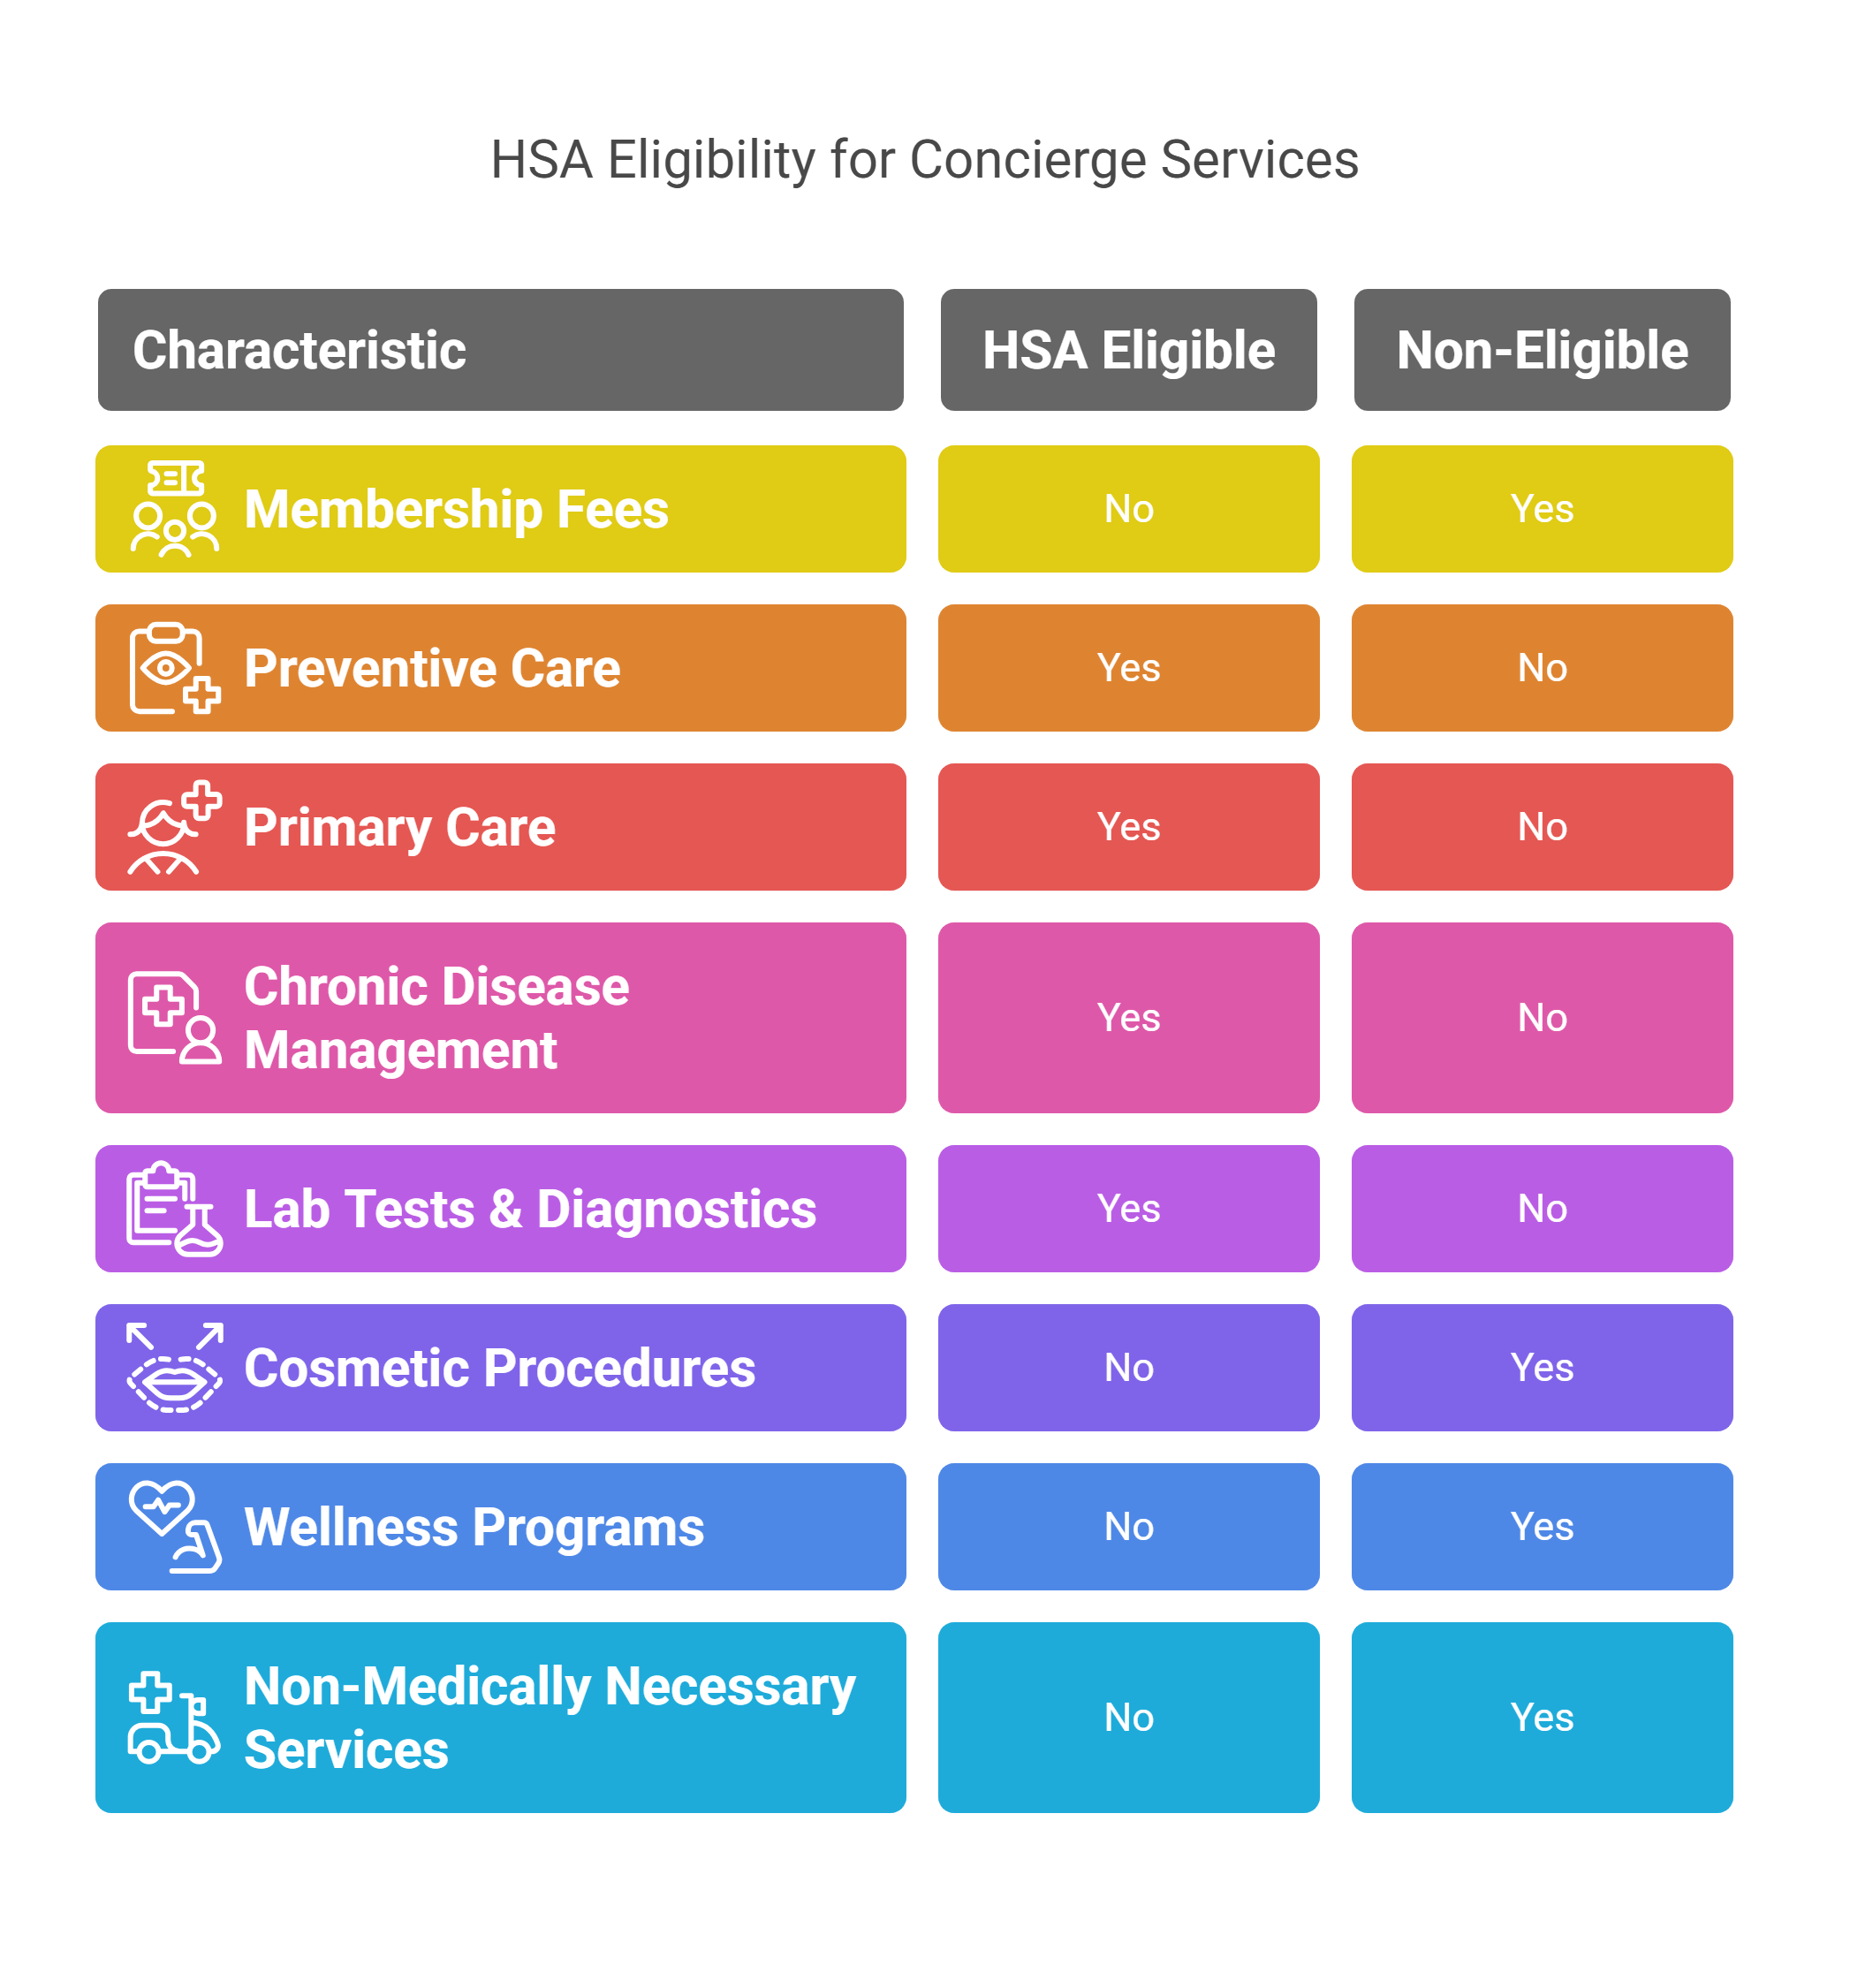
If you are unsure whether your HSA will cover a medical expense, remember this general rule: eligibility for HSA funds is determined by whether the expense qualifies as "medical care" under Section 213(d) of the Internal Revenue Code, which includes costs for diagnosis, cure, mitigation, treatment, or prevention of disease. It is not based on whether insurance normally pays for it.
Following this IRS guidance, your Health Savings Account generally cannot pay for your concierge medicine membership fees if those fees are solely for access or availability, as these are typically not considered qualified medical expenses . Starting in 2026, direct primary care fees can be paid from an HSA if the arrangement meets the IRS rules. Those rules include a fixed periodic fee of no more than $150 a month for one person or $300 a month for more than one person, with only primary care services. Many concierge retainers cost more than that limit or bill insurance too, so ask the practice and a tax adviser. Outside of that rule, you can still use your HSA for specific, itemized qualified medical services your concierge doctor offers. You can:
In any case, make sure to get an itemized bill from your doctor. Detailed records would come very useful should the IRS audit you.
Your HSA generally cannot pay a concierge access or retainer fee, but you may still be able to use HSA funds for qualified medical services that your doctor bills separately.
If your doctor bills you for a specific qualified medical service, such as a lab test, you can pay for it or reimburse yourself through your HSA. This will not cover the membership fee, but it may help reduce your out-of-pocket expense for actual medical care received. Only services that were really provided and billed at their true price can be reimbursed, and fees should never be renamed or split up just to make them qualify. Ask a tax adviser if you are unsure.
Better yet, ask your concierge doctor which services are billed separately and may count as qualified medical expenses. This will give you a better sense of your medical expenses under concierge medicine.
Concierge medicine and Health Savings Account (HSA) can work together to help you manage your medical costs for eligible services.
Now how to choose a concierge doctor? Helping patients like you find a doctor who fits their needs is our goal. You can also find a concierge doctor in your area.
Purely access or retainer-based membership fees in Concierge Medicine are generally not covered by your Health Savings Account (HSA) as they are typically not considered qualified medical expenses by the IRS . However, if your concierge practice provides specific, itemized medical services that meet the IRS definition of medical care, those specific service costs may be reimbursable via your HSA.
The rule of thumb here is this: an expense is HSA-eligible if it meets the IRS definition of "medical care" under Section 213(d) of the Internal Revenue Code. This means that, although your HSA generally cannot cover your Concierge membership fees if they are for access only, there are particular qualified medical services within your membership (if itemized separately) which can be reimbursed using your HSA.
Although your HSA generally cannot cover your Concierge Medicine membership fee if it's solely for access , what you can do is to simply pull funds from your HSA and pay your Concierge doctor directly for specific, itemized qualified medical services rendered. No need to worry about getting taxed – this is accepted because fees for actual medical care from a physician are considered a qualified medical expense.
There are ways you can utilize your HSA to pay for specific, itemized qualified medical services within your Concierge Medicine arrangement, even though your purely access-based membership or subscription fee is generally not an eligible expense under your HSA. Make sure to check which Concierge services are qualified medical expenses and always ask your doctor for an itemized invoice so that processing your reimbursements are a breeze.
Concierge membership fees that are solely for access or availability are generally not HSA eligible , although fees for specific, qualified medical services rendered by a doctor are HSA reimbursable. A way to properly use HSA funds is to go over the list of medical services included in your membership and see which ones are itemized as qualified medical expenses eligible for HSA payment or reimbursement.
While your entire Concierge membership fee (if it includes charges for access/availability) generally cannot be covered by HSA, there are specific qualified medical services within your Concierge arrangement which, if itemized, may be HSA reimbursable. This can still merit you significant medical savings so taking time to do your research on IRS rules for qualified medical expenses is very important.
No, you generally cannot use your HSA to cover medical membership fees in Direct Primary Care and Concierge Medicine subscriptions if these fees are solely for access or availability rather than for specific medical services rendered . On the other hand, there are specific medical services provided under your membership which can be reimbursed through your HSA if they are qualified medical expenses and properly itemized.
Purely access-based Concierge fees are generally not HSA eligible, but there are certain charges within your Concierge subscription which are qualified for HSA reimbursement – fees for specific, itemized qualified medical services rendered by a doctor are one of them.